
CFO Message
CFO (Chief Financial Officer) Masaaki Yamamoto
Review of FY2025 performance
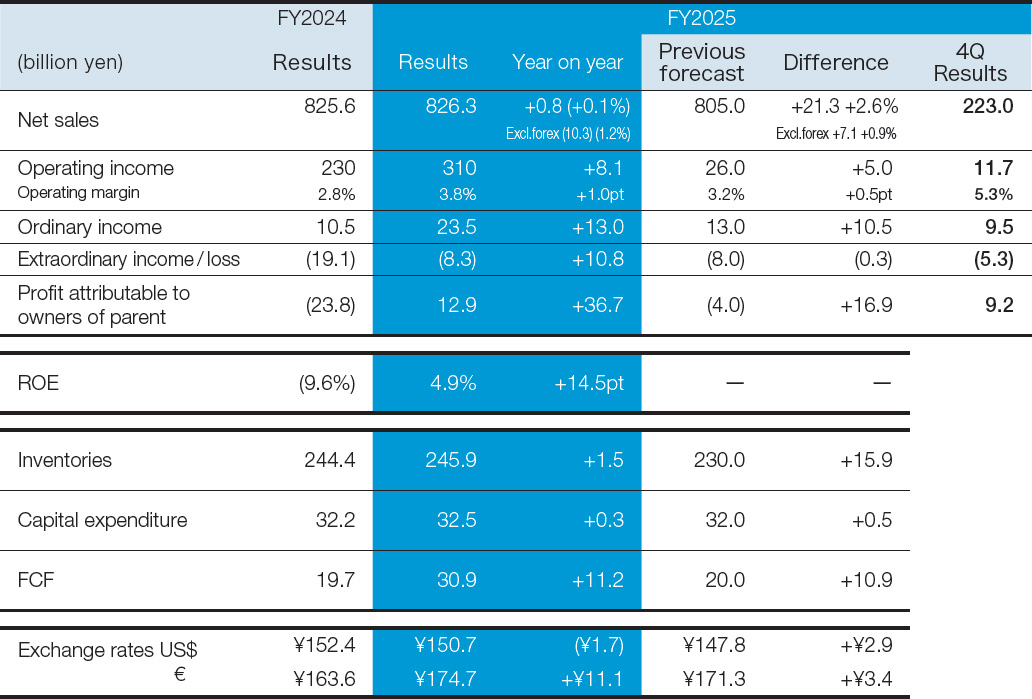
Our Group launched the Medium-term Management Plan “DRIVE NTN100” Final in April 2024. In FY2025, the second year of this plan, demand for automotive applications remained sluggish; however, net sales reached 826.3 billion yen (up 0.1% from the previous year), supported by increased demand in the aftermarket and industrial machinery segments, as well as the effect of yen depreciation.
Operating income reached 31.0 billion yen (up 34.8% from the previous year), reflecting improvements in selling prices and variable costs, cost reductions, and the impact of exchange rates. Ordinary income was 23.5 billion yen (up 124% from the previous year) due to reduced foreign exchange losses. Net profit attributable to owners of parent was 12.9 billion yen, as we recorded extraordinary losses mainly due to structural reform costs, and the impact of tax effect accounting in Japan.
What we place greater emphasis on, however, is the extent to which our ability to generate cash has improved. In FY2025, progress was made in improving working capital, including a reduction in inventories, resulting in operating cash flow of 57.2 billion yen and free cash flow of 30.9 billion yen, both positive. Inventories totaled 245.9 billion yen, and excluding the impact of foreign exchange and U.S. tariffs, we achieved our target. In addition to improved profitability, our transformation into a business structure capable of reliably generating cash demonstrates that our management foundation is becoming increasingly robust.
Corporate value is formed as the sum of the present value of cash flows generated over the future. In this sense, we recognize that the achievements of FY2025 go beyond mere improvement in profits for a single fiscal year and are steadily contributing to the enhancement of corporate value through improved cash generation capacity.
The most fundamental objective for any company is to ensure its survival and the continuity of its business operations. In FY2025, amid significant fluctuations in the external environment, we were required to make numerous judgments; however, our guiding criterion of “business continuity” never wavered. We believe that our FY2025 results reflect the steady execution of initiatives necessary to ensure business continuity, including structural reform.
Progress of structural reform and business constitution improvements
Advances in structural reform and business constitution improvements
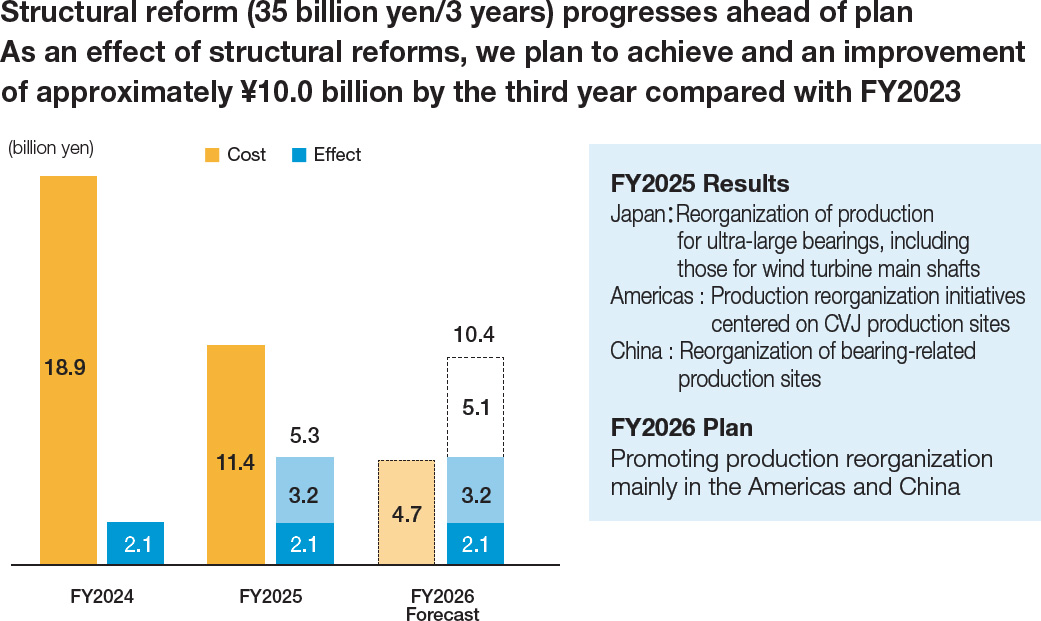
Our Group anticipates extraordinary losses of 35.0 billion yen in total over the three-year period from FY2024 to FY2026 as costs for structural reform. In line with this, we recorded extraordinary losses of 18.9 billion yen in FY2024. In FY2025, we recorded extraordinary losses of 11.4 billion yen as a result of reviewing the production structure in Japan for extralarge bearings, including those for wind turbine main shafts, optimizing CVJ production bases in the Americas, and reorganizing bearing-related production bases in China.
While the plan to record cumulative extraordinary losses of 35.0 billion yen over three years is exceptional, we view this as an essential measure to secure future business continuity and strengthen our business structure in terms of both profitability and capital efficiency. In FY2026, we will continue to advance production reorganization, primarily in the Americas and China. As a result of these structural reform initiatives, we expect fixed cost reductions of approximately 10.0 billion yen in FY2026 compared to FY2023.
The significance of these structural reforms does not end with short-term cost recognition. The essence lies in enhancing future profitability and cash generation capacity through optimization of fixed costs, consolidation of business sites, and productivity improvements, thereby contributing to the enhancement of corporate value. By advancing profit improvement and the strengthening of cash generation capacity in an integrated manner, our Group is working to transform toward a leaner business structure.
Inventory reduction and improvement of turnover ratio
Reducing inventories, mainly work-in-process inventory, is essential for improving asset efficiency.
Our Group has focused on production reform activities to reduce inventory levels, which had previously been high. The production reform activities are designed to drive a change in employee mindset based on the principle that “the only time that generates cash is the time spent processing, and it is important to reduce the time spent stagnating.” These activities began at our domestic sites and have since spread to our overseas operation, where they are now delivering results.
As a result, the inventory turnover ratio at the end of FY2025 was 3.4 times. Excluding the impact of volume decline, we recognize that we have reached a level close to our target. The improvement in operating cash flow was driven in large part by the collective efforts of employees involved in purchasing, manufacturing, and sales to reduce inventories.
We expect the inventory balance at the end of FY2026 to be 220.0 billion yen, a decrease of 25.9 billion yen from the previous fiscal year-end, and the inventory turnover ratio to be 3.7 times, an improvement of 0.3 times from the previous year. Going forward, we will continue to reduce inventories and improve the turnover ratio, leading to not only improved profitability, but also enhanced cash generation capacity.
Roadmap to achieving 8% ROE
Throughout the three years of “DRIVE NTN100” Final, our Group has worked to strengthen our financial foundation and transform toward a leaner business structure. In addition to the deterioration of the external environment—including the prolonged Ukraine war, U.S. trade policy, and dramatic changes in the situation in the Middle East—the relative decline in competitiveness of Japanese automotive manufacturers has also had an impact, and our current sales scale is nearly 100.0 billion yen below the assumptions of the Medium-term Management Plan. Even amid such an environment, we have accelerated structural reform activities while steadily implementing measures that contribute to improving operating margin, such as “expansion of the aftermarket business,” “improvement of selling prices,” and “reduction of variable costs through value chain reform,” as well as reduction in inventories and fixed assets. As a result, ROE, which had fallen to minus 9.6% at the end of FY2024, has recovered to 4.9% at the end of FY2025, an improvement of plus 14.5 percentage points.
While our Group positions ROE as a key management indicator, we believe that its improvement should be supported not only by the recovery of profits, but also by improvements in asset efficiency and cash generation capacity. Indeed, improvements in working capital, including inventories, and the efficient use of fixed assets contribute to both improved capital efficiency and the enhancement of corporate value. In the final year of “DRIVE NTN100” Final, we expect net sales to decline by 16.3 billion yen compared to FY2025; however, we expect ROE to improve further through the continuation of various improvement initiatives. Going forward, we will continue to strengthen our business structure, aiming for the early achievement of 8% ROE in the next Medium-term Management Plan.
Cash allocation
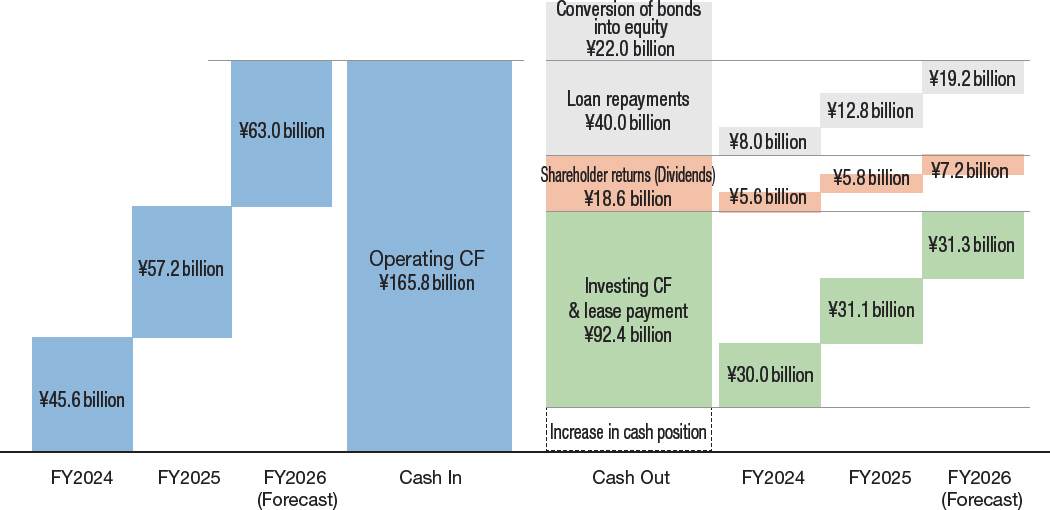
Regarding cash allocation, at the time of formulating the Medium-term Management Plan, we assumed total cash inflows of 200.0 billion yen, comprising operating cash flow of 180.0 billion yen over three years and cash and cash equivalents of 20.0 billion yen. On the cash outflow side, we planned debt repayment of 60.0 billion yen, investing cash flow of 120.0 billion yen, and shareholder returns of 20.0 billion yen.
As of the end of FY2026, operating cash flow is expected to be slightly below the initial plan at just under 170.0 billion yen. On the other hand, while we had assumed drawing down 20.0 billion yen in cash and cash equivalents for debt repayment, convertible bonds of 22.0 billion yen, which were not incorporated in the initial plan, were converted into equity. As a result, while we had initially planned to reduce net interest-bearing debt by 40.0 billion yen over three years, we now expect to reduce it by approximately 62.0 billion yen including the convertible bonds. Regarding shareholder returns, while we had planned 20.0 billion yen over three years, we now expect approximately 19.0 billion yen. Overall, we believe we will be able to maintain the direction of the initial plan.
In a business environment where sales scale declined significantly from the first year of the Medium-term Management Plan, management as a whole shared a sense of urgency and worked together to accelerate the implementation of various measures. We recognize that the results of these efforts are steadily materializing not only in terms of improved profits, but also in the form of improved cash flow and financial structure.
Financial strategy direction
While the next Medium-term Management Plan is currently under consideration, we are working to further embed ROIC—a metric we have long used as a key evaluation indicator—throughout the organization and on-site operations. To help employees understand ROIC, we have encouraged a change in mindset by asking them, “How would you feel if something you bought with your own money sat unused in a corner of your home?” These efforts are steadily beginning to bear fruit, and improvements in ROIC are also contributing to improvements in ROE.
Going forward, while continuing structural reform, we are also considering investments in India, a growth market. By business segment, we will advance a shift toward higher value-added areas in automotive OEM, where the ratio of Japanese customers is high, while accelerating business expansion in aircraft-related fields including defense—a growth area outside of automotive—by also leveraging our European manufacturing bases. In addition, we will continue to invest in technological development, the realization of carbon neutrality, labor-saving measures, and digitalization, steadily improving both ROE and ROIC.
Through improvements in profitability, enhanced asset efficiency including inventories, our financial foundation has been steadily strengthened. Going forward, we will appropriately allocate these achievements to growth investments, the maintenance and enhancement of financial soundness, and shareholder returns, thereby contributing to the sustainable enhancement of corporate value.
The external environment remains unpredictable; however, we are committed to translating these ongoing initiatives into tangible results. With the achievement of a PBR of 1x and the sustainable generation of profits exceeding the cost of capital positioned as our top priorities, the entire NTN Group will work together toward achieving the targets of the final year of “DRIVE NTN100” Final. We ask for the continued support and encouragement of all our stakeholders.